2026 Federal Reserve Interest Rate Hikes: 3-Month Analysis
Anúncios
Understanding the immediate financial implications of the 2026 Federal Reserve interest rate hikes is crucial for individuals and businesses across the United States.
Anúncios
As we step into 2026, the financial landscape remains a dynamic and often unpredictable terrain. For many, the phrase “interest rate hikes” can conjure images of economic uncertainty. However, by proactively understanding and preparing for the changes, individuals and businesses can navigate these shifts effectively. This article delves into Navigating the 2026 Federal Reserve Interest Rate Hikes: A 3-Month Financial Impact Analysis, offering insights and strategies to adapt.
Understanding the Federal Reserve’s Role in 2026
The Federal Reserve, often simply called “the Fed,” serves as the central bank of the United States. Its primary mandate involves maintaining maximum employment, stable prices, and moderate long-term interest rates. In 2026, the Fed’s decisions regarding interest rates will continue to be a critical determinant of economic health and individual financial well-being. These decisions are not made in a vacuum; they are a response to inflationary pressures, employment figures, and overall economic growth trends.
When the Fed raises interest rates, it typically aims to curb inflation by making borrowing more expensive, thereby slowing down economic activity. Conversely, lowering rates is intended to stimulate growth. For 2026, the expectation of further hikes stems from persistent inflationary concerns and a robust labor market that might still show signs of overheating. Understanding this foundational role is the first step in deciphering the potential impacts on your finances.
The Mechanics of Rate Hikes
The Fed directly influences the federal funds rate, which is the target rate for overnight lending between banks. While this isn’t the rate consumers directly encounter, it serves as a benchmark that influences a cascade of other rates throughout the economy. When the federal funds rate rises, commercial banks typically adjust their prime rate, which then affects a wide array of consumer and business loans.
- Prime Rate Adjustments: Directly impacts variable-rate loans.
- Mortgage Rate Shifts: Influences affordability of new homes and refinancing.
- Credit Card APRs: Often see immediate increases.
- Savings Account Yields: Can eventually rise, benefiting savers.
These adjustments happen relatively quickly, making it imperative for individuals and businesses to anticipate and react to these changes. The initial three months following a rate hike are particularly crucial, as the market begins to digest and incorporate the new cost of borrowing.
The Federal Reserve’s actions in 2026 will be closely watched, as their decisions ripple through every corner of the financial system. Their commitment to price stability, while essential for long-term economic health, can create short-term challenges for borrowers and opportunities for savers. Staying informed about their policy statements and economic forecasts is key to informed financial planning.
Immediate Impact on Consumer Lending: Month 1-3 Post-Hike
The moment the Federal Reserve announces an interest rate hike, the financial markets begin to react, and consumers feel the effects almost immediately, particularly on variable-rate loans. The first three months following such an announcement are a critical period where these changes translate into real-world costs for households across the United States.
Credit card interest rates are often among the first to adjust. Most credit cards have variable annual percentage rates (APRs) tied to the prime rate, which moves in lockstep with the federal funds rate. This means that within a billing cycle or two, consumers carrying a balance will see their minimum payments increase, potentially making it harder to pay down debt.
Credit Card Debt and Personal Loans
For those with significant credit card debt, even a slight increase in the APR can add up over time. A 0.25% or 0.50% hike might seem small, but on a large balance, it translates into dozens, or even hundreds, of extra dollars in interest paid annually. Personal loans, especially those with variable rates, will also see their interest charges rise, impacting monthly budgets.
- Increased Minimum Payments: Higher interest means larger minimum payments on credit card balances.
- Slower Debt Reduction: More of each payment goes to interest, prolonging debt repayment.
- Budget Strain: Reduced disposable income due to higher debt service costs.
Consumers should prioritize paying down high-interest debt during this period. Consolidating debt into a fixed-rate loan, if available and affordable, could be a strategic move to insulate against future rate increases. The first three months are a window of opportunity to assess and adjust debt management strategies before the full weight of the hikes is felt.
Mortgage Market Dynamics and Homeownership in 2026
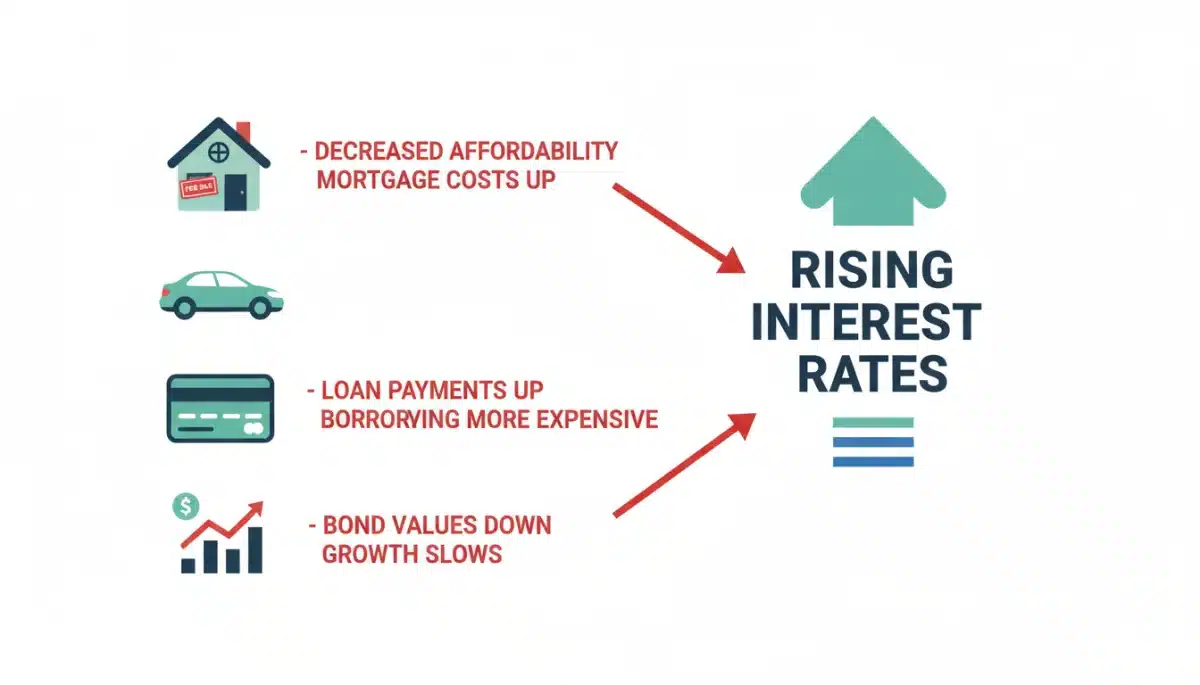
The housing market is highly sensitive to interest rate fluctuations, and the 2026 Federal Reserve interest rate hikes will undoubtedly reshape its landscape. While existing fixed-rate mortgage holders are largely insulated, those looking to buy a home, refinance, or with adjustable-rate mortgages (ARMs) will experience direct and significant impacts, particularly within the initial three-month period.
Rising interest rates translate directly into higher borrowing costs for new mortgages. This means that the same loan amount will come with a higher monthly payment, effectively reducing purchasing power for prospective homebuyers. For a typical home purchase, even a modest rate increase can add hundreds of dollars to a monthly mortgage bill, potentially pricing some buyers out of the market entirely.
Anúncios
Adjustable-Rate Mortgages (ARMs)
Homeowners with adjustable-rate mortgages (ARMs) are particularly vulnerable to rate hikes. These loans typically have an initial fixed-rate period, after which the interest rate adjusts periodically based on a predetermined index, which is often tied to the federal funds rate. Within the first three months of a Fed hike, many ARMs will see their rates reset higher, leading to increased monthly payments.
- Higher Monthly Payments: Directly impacts homeowners with ARMs.
- Refinancing Challenges: Less attractive for homeowners seeking lower rates.
- Reduced Affordability: New buyers face higher costs, potentially slowing sales.
The initial three months are crucial for ARM holders to review their loan terms and consider options like refinancing into a fixed-rate mortgage, if still financially advantageous, or preparing for higher payments. For new buyers, carefully calculating affordability and understanding the long-term cost of borrowing becomes even more paramount. The market may see a temporary slowdown as buyers adjust to the new economic reality.
Impact on Business Borrowing and Investment Decisions
Businesses, from small startups to large corporations, rely on borrowed capital for expansion, inventory, and operational needs. The 2026 Federal Reserve interest rate hikes will significantly influence their borrowing costs and, consequently, their investment decisions. The initial three-month period post-hike will be critical for businesses to reassess their financial strategies and adapt to the new economic environment.
Higher interest rates mean that the cost of taking out new loans, or servicing existing variable-rate debt, increases. This directly impacts a company’s bottom line. For businesses planning major capital expenditures, such as purchasing new equipment, expanding facilities, or investing in research and development, the hurdle rate for these projects effectively rises. Projects that seemed viable at lower rates might become less attractive or even unfeasible.
Small Business Lending Landscape
Small businesses, which often have less access to diverse funding sources than larger corporations, can feel the pinch more acutely. Their lines of credit and term loans are frequently tied to the prime rate, meaning an immediate increase in their cost of capital. This can lead to reduced hiring, delayed expansion plans, and a tighter focus on cost control.
- Increased Loan Costs: Higher interest on new and existing variable-rate debt.
- Delayed Expansion: Businesses may postpone or scale back investment projects.
- Tighter Profit Margins: Increased borrowing costs can squeeze profitability.
The first three months demand a thorough review of financial obligations and future investment plans. Businesses might explore alternative financing options, optimize their cash flow management, and prioritize projects with the highest immediate return on investment. The ability to quickly adapt to these rising costs will differentiate successful businesses in this challenging environment.
Savings and Investment Strategies in a Rising Rate Environment
While rising interest rates present challenges for borrowers, they often create opportunities for savers and investors. The 2026 Federal Reserve interest rate hikes will gradually make holding cash and fixed-income investments more attractive. Over the initial three months, we can expect to see shifts in where individuals and institutions choose to park their money, seeking better returns.
Traditional savings accounts, money market accounts, and Certificates of Deposit (CDs) typically offer higher yields in a rising rate environment. While these increases might not be immediate or dramatic, especially for standard savings accounts, they gradually improve the return on low-risk deposits. This provides a welcome change for savers who have endured years of historically low interest rates.
Bonds and Fixed Income
For investors, the fixed-income market becomes more complex. Newly issued bonds will offer higher yields, making them more appealing. However, existing bonds with lower fixed rates will generally decrease in value as new, higher-yielding alternatives become available. This inverse relationship between interest rates and bond prices is a crucial consideration for portfolio management.
- Higher Savings Yields: Improved returns on bank deposits and money market accounts.
- Attractive New Bonds: Opportunities for investors to lock in higher fixed-income returns.
- Portfolio Rebalancing: Potential need to adjust bond holdings to mitigate existing bond value depreciation.
Over the first three months, individuals should evaluate their cash holdings and consider moving funds to higher-yield savings products or short-term CDs. Investors might look at adjusting their bond portfolios, perhaps favoring shorter-duration bonds to minimize interest rate risk, or carefully selecting new bond issues. The goal is to capitalize on the higher returns available while managing the risks associated with existing fixed-income assets.
Broader Economic Implications and Regional Variances
The 2026 Federal Reserve interest rate hikes will not only affect individual finances and business operations but also have broader implications for the U.S. economy, with regional variances. The initial three-month analysis period offers a glimpse into how different sectors and geographical areas might respond to these monetary policy changes. Economic activity often slows down as borrowing becomes more expensive, potentially leading to a moderation in inflation but also a risk of reduced growth.
Sectors that are heavily reliant on consumer borrowing, such as housing and automotive, are likely to experience a slowdown. Discretionary spending may also decrease as households face higher debt servicing costs. Conversely, sectors less sensitive to interest rates, or those that benefit from a stronger dollar (a potential side effect of higher rates), might fare better. The overall aim of the Fed is to achieve a “soft landing” – cooling inflation without triggering a recession.
Regional Economic Divergence
The impact of rate hikes is rarely uniform across the United States. Regions with booming housing markets or those heavily dependent on manufacturing or consumer spending might feel the effects more acutely. For instance, areas with a high concentration of tech startups, which often rely on venture capital and easy access to credit, could see a slowdown in investment.
- Sectoral Slowdown: Housing, auto, and discretionary retail may face headwinds.
- Potential for Job Market Shifts: Some industries might experience slower hiring.
- Stronger Dollar Impact: Benefits importers but can hurt exporters.
During the first three months, economic indicators such as retail sales, housing starts, and manufacturing output will be closely watched for signs of how the economy is absorbing the rate increases. Policymakers will analyze these regional and sectoral responses to gauge the effectiveness of their actions and consider future adjustments. Understanding these broader economic currents is vital for both individuals and businesses to make informed decisions.
Strategies for Financial Resilience in 2026
In light of the 2026 Federal Reserve interest rate hikes, adopting proactive financial strategies is paramount for building resilience. The first three months following any rate increase are a crucial period for assessment and adjustment. Whether you are an individual managing household finances or a business owner overseeing capital, strategic planning can mitigate negative impacts and even uncover new opportunities.
For individuals, reviewing and optimizing budgets is a critical first step. Identifying areas where spending can be reduced, and allocating more funds towards high-interest debt, can significantly alleviate financial strain. Building an emergency fund becomes even more important, providing a buffer against unexpected costs or income disruptions in a potentially cooling economy.
Personal and Business Adaptations
Businesses should focus on strengthening their balance sheets and optimizing operational efficiency. This might involve renegotiating supplier contracts, streamlining inventory management, or exploring new markets. Access to capital might become more expensive, so judicious use of existing funds and a clear investment strategy are essential.
- Prioritize Debt Reduction: Focus on high-interest credit cards and variable-rate loans.
- Strengthen Emergency Funds: Aim for at least 3-6 months of living expenses.
- Re-evaluate Investment Portfolios: Consider assets that perform well in rising rate environments.
- Optimize Business Operations: Enhance efficiency and manage cash flow effectively.
The initial three months provide a window to consult with financial advisors or business consultants to tailor strategies specific to your situation. This period is not just about reacting to changes but about proactively positioning yourself for long-term stability and growth. Resilience in 2026 will be defined by adaptability and a commitment to sound financial principles.
| Key Financial Area | 3-Month Impact Summary |
|---|---|
| Consumer Debt | Credit card APRs and variable personal loan rates likely increase, raising monthly payments. |
| Mortgage Market | New mortgage rates rise, reducing affordability; ARM payments may increase. |
| Business Borrowing | Cost of capital increases, potentially delaying investment and expansion plans for businesses. |
| Savings & Investments | Savings account yields may improve; new bonds offer higher returns, but existing bond values may fall. |
Frequently Asked Questions About 2026 Rate Hikes
Credit card APRs, being variable, often adjust very quickly, usually within one to two billing cycles after a Federal Reserve rate hike. This means you could see higher interest charges on your outstanding balance almost immediately.
No, if you have a fixed-rate mortgage, your interest rate and monthly payments will not change due to Federal Reserve rate hikes. These increases primarily affect new loans and adjustable-rate mortgages (ARMs).
Small businesses should review their current debt, optimize cash flow, and potentially secure fixed-rate financing if available. Prioritizing essential investments and focusing on operational efficiency can help mitigate the impact of rising rates.
As a saver, you can benefit by seeking higher yields on savings accounts, money market accounts, and Certificates of Deposit (CDs). Compare rates from various financial institutions to ensure your cash is earning the best possible return.
The Federal Reserve’s primary goal with interest rate hikes is to combat inflation and ensure price stability. By making borrowing more expensive, they aim to slow down economic activity and reduce demand, which can help bring inflation back to target levels.
Conclusion
Navigating the 2026 Federal Reserve Interest Rate Hikes: A 3-Month Financial Impact Analysis reveals a landscape where proactive financial management is key. The initial three months following any rate adjustment are crucial for understanding and adapting to the evolving economic environment. While borrowers face increased costs, savers and investors may find new opportunities for growth. By staying informed, reviewing personal and business financial health, and implementing strategic adjustments, individuals and businesses can build greater resilience and navigate the shifts with confidence. The ability to adapt quickly and effectively will be a defining factor in maintaining financial stability throughout 2026 and beyond.
