Unlocking 2026 Social Security Benefits: Your Optimal Claiming Guide
Anúncios
Understanding how to claim your 2026 Social Security benefits at the optimal age is crucial for maximizing your retirement income and ensuring financial stability in the coming years.
Anúncios
Are you approaching retirement and wondering how to navigate the complexities of Social Security? As we look towards 2026, understanding how to maximize your benefits is more critical than ever. This guide provides practical, step-by-step solutions for 2026 Social Security Benefits, helping you determine your optimal claiming age and secure your financial future.
Understanding Social Security in 2026: The Basics
Social Security remains a cornerstone of retirement planning for millions of Americans. By 2026, the program will continue to adapt to economic shifts and demographic changes, making it essential for prospective retirees to stay informed about the latest regulations and benefit structures. Knowing the fundamentals is the first step toward making informed decisions about your financial well-being.
The Social Security Administration (SSA) continuously evaluates its policies to ensure the program’s long-term solvency. While core principles remain, minor adjustments can significantly impact individual benefits. These adjustments often relate to cost-of-living adjustments (COLAs), earnings limits, and the definition of full retirement age (FRA).
Key Social Security Concepts for 2026
Before diving into claiming strategies, it’s vital to grasp a few fundamental concepts that will govern your benefits in 2026:
- Full Retirement Age (FRA): This is the age at which you are entitled to receive 100% of your primary insurance amount (PIA). For those born in 1960 or later, FRA is 67. Claiming before or after this age will adjust your benefits.
- Primary Insurance Amount (PIA): Your PIA is the benefit amount you would receive if you start collecting benefits at your full retirement age. It’s calculated based on your average indexed monthly earnings (AIME) over your 35 highest-earning years.
- Cost-of-Living Adjustments (COLAs): Social Security benefits are typically adjusted annually to keep pace with inflation. These COLAs ensure that the purchasing power of your benefits doesn’t erode over time.
Understanding these basic tenets provides a solid foundation for exploring more advanced claiming strategies. The decisions you make regarding when and how to claim your benefits can have lasting implications, so a thorough understanding is paramount.
Determining Your Full Retirement Age (FRA) for 2026
Your Full Retirement Age (FRA) is a pivotal factor in calculating your Social Security benefits. It’s not a one-size-fits-all number; rather, it depends on your birth year. For individuals born in 1960 or later, the FRA is 67. Understanding your specific FRA is crucial because it dictates when you can receive your full, unreduced benefits.
Claiming benefits before your FRA results in a permanent reduction, while delaying benefits past your FRA can significantly increase your monthly payment. This flexibility allows individuals to tailor their claiming strategy to their personal circumstances, health, and financial needs. It’s a calculation that demands careful consideration, as it directly impacts your long-term financial security.
FRA Schedule and Implications
The FRA schedule was gradually increased over several decades to account for increased life expectancy. For those planning their retirement in 2026, knowing this exact age is the first step in strategic claiming.
- Born 1943-1954: FRA is 66.
- Born 1955: FRA is 66 and 2 months.
- Born 1956: FRA is 66 and 4 months.
- Born 1957: FRA is 66 and 6 months.
- Born 1958: FRA is 66 and 8 months.
- Born 1959: FRA is 66 and 10 months.
- Born 1960 or later: FRA is 67.
The implications of your FRA are profound. If you claim at age 62, the earliest possible age, your benefits will be permanently reduced by approximately 30% compared to your PIA. Conversely, for each year you delay claiming past your FRA, up to age 70, you earn delayed retirement credits, increasing your benefit by 8% per year. This means a significant difference in your monthly income over the course of your retirement.
Therefore, identifying your precise FRA is not just an administrative detail; it’s a strategic move that sets the foundation for all subsequent decisions regarding your Social Security benefits.
Early vs. Delayed Claiming: Maximizing Your 2026 Benefits
The decision of when to claim your Social Security benefits is one of the most significant financial choices you’ll make in retirement. It’s a complex equation involving your health, financial needs, life expectancy, and even your family situation. Understanding the trade-offs between early and delayed claiming is crucial for maximizing your 2026 Social Security Benefits.
Anúncios
Claiming early, as soon as age 62, provides immediate income but at a permanently reduced rate. This can be appealing for those who need funds immediately, are facing health challenges, or simply want to retire sooner. However, delaying your claim past your Full Retirement Age (FRA) can lead to substantially higher monthly payments, offering a significant financial advantage over the long term.
The Trade-Offs of Early Claiming (Age 62)
Opting for early claiming at age 62 means you’ll receive benefits sooner, which can be advantageous if you have immediate financial needs or if your life expectancy is shorter. However, this comes with a permanent reduction in your monthly benefit.
- Benefit Reduction: Your monthly benefit will be reduced by up to 30% compared to your PIA. This reduction is permanent.
- Earnings Limit: If you continue to work while claiming early benefits, your benefits may be temporarily withheld if your earnings exceed a certain limit. This limit changes annually, so it’s important to check the SSA’s current figures for 2026.
- Spousal Benefits: Claiming early can also impact spousal benefits, potentially reducing the amount your spouse might receive based on your record.
While early claiming offers immediate cash flow, it often means sacrificing a larger monthly check later on. This choice should align with your overall financial plan and personal circumstances.
The Advantages of Delayed Claiming (Up to Age 70)
Delaying your claim past your FRA, up to age 70, can significantly boost your monthly Social Security income. For each year you delay past your FRA, your benefit increases by 8% due to delayed retirement credits.
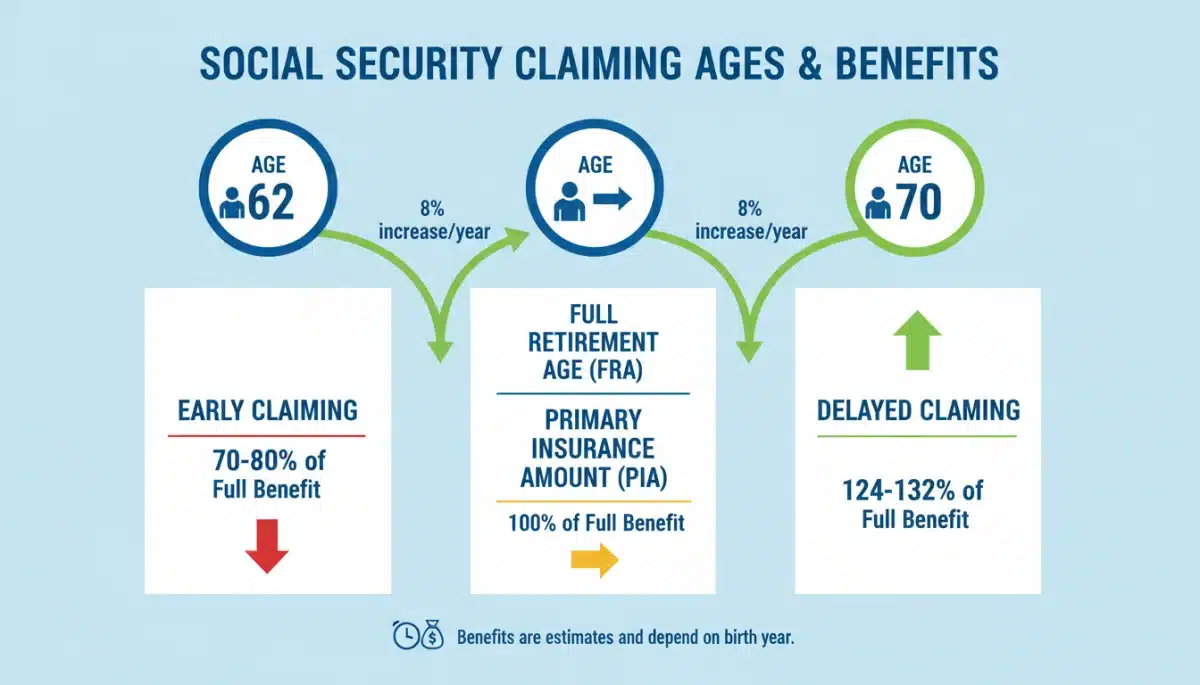

- Higher Monthly Benefit: Delaying until age 70 can result in a monthly benefit that is 24% to 32% higher than your PIA, depending on your FRA.
- Inflation Protection: These higher benefits are also subject to annual Cost-of-Living Adjustments (COLAs), providing greater protection against inflation.
- Survivor Benefits: A higher monthly benefit also translates to a higher survivor benefit for your spouse if you predecease them.
Delayed claiming is often recommended for those who are in good health, have other retirement income sources, or simply want to maximize their guaranteed lifetime income. The increased monthly payments can provide a significant buffer against rising living costs and unforeseen expenses in later life. The decision between early and delayed claiming requires careful consideration of your unique situation and long-term financial goals.
Spousal and Survivor Benefits: What You Need to Know for 2026
Social Security isn’t just about individual retirement benefits; it also provides crucial financial support for spouses and survivors. Understanding these provisions for 2026 Social Security Benefits can significantly impact a family’s financial planning, especially when one spouse has a considerably higher earning record or in the event of a spouse’s passing. These benefits offer a safety net, but their complexities often require careful navigation.
Spousal benefits allow an eligible spouse to claim benefits based on their partner’s work record, even if they have little or no work history themselves. Survivor benefits, on the other hand, provide financial assistance to surviving family members after a worker’s death. Both types of benefits have specific eligibility criteria and claiming rules that can affect the amount received.
Claiming Spousal Benefits
For 2026, spousal benefits generally allow a spouse to receive up to 50% of the working spouse’s Primary Insurance Amount (PIA) at their own full retirement age (FRA). However, claiming spousal benefits before your FRA will result in a permanent reduction.
- Eligibility: You must be married for at least one year to claim spousal benefits. If divorced, the marriage must have lasted at least 10 years, and you must currently be unmarried.
- Impact of Your Own Record: If you are eligible for benefits on your own work record, the SSA will pay you the higher of your own benefit or your spousal benefit. You cannot receive both in full.
- “File and Suspend” is Gone: The “file and suspend” strategy, which allowed one spouse to file for benefits while the other delayed, has been eliminated. This means strategic timing is even more critical.
Careful coordination between spouses is essential to maximize combined benefits. Often, the higher earner delays claiming to boost their own benefit (and thus potential survivor benefits), while the lower earner may claim spousal benefits or their own, depending on which is greater.
Understanding Survivor Benefits
Survivor benefits provide a lifeline to widows, widowers, and eligible children after a worker’s death. The amount depends on the deceased worker’s earnings and the survivor’s age and relationship.
- Widow(er)’s Benefits: A surviving spouse can claim benefits as early as age 60 (or age 50 if disabled). If they claim before their own FRA, the benefits will be reduced. At their FRA, they can receive 100% of the deceased worker’s benefit.
- Children’s Benefits: Unmarried children under 18 (or 19 if still in high school) can receive benefits. Disabled children can receive benefits at any age if their disability began before age 22.
- Maximum Family Benefit: There’s a limit to the total amount of benefits that can be paid to a family based on one worker’s record, typically between 150% and 180% of the worker’s PIA.
Survivor benefits are a critical component of financial security, especially for families who lose a primary income earner. Understanding these rules ensures that eligible family members receive the support they are entitled to. Planning for these eventualities is a thoughtful part of comprehensive retirement and estate planning.
Practical Steps for Claiming Your 2026 Social Security Benefits
Navigating the Social Security claiming process can seem daunting, but breaking it down into practical steps makes it manageable. As you prepare to claim your 2026 Social Security Benefits, having a clear roadmap will ensure a smooth application and help you avoid common pitfalls. The process involves gathering necessary documentation, understanding application methods, and knowing what to expect after you apply.
The Social Security Administration (SSA) offers various ways to apply, and choosing the most convenient and efficient method for your situation can save you time and stress. Regardless of your chosen method, thorough preparation is key to a successful claim.
Before You Apply: Essential Preparations
Before you even think about submitting an application, there are several crucial steps to take:
- Create an Online Account: Visit the SSA website to create a “my Social Security” account. This allows you to check your earnings record, estimate future benefits, and monitor your application status.
- Review Your Earnings Record: Ensure your earnings record is accurate. Any discrepancies could affect your benefit amount. Report any errors to the SSA immediately.
- Gather Necessary Documents: You’ll need documents such as your birth certificate, Social Security card, proof of U.S. citizenship or lawful alien status (if not born in the U.S.), W-2 forms or self-employment tax returns for the past two years, and bank account information for direct deposit.
Being well-prepared with all documentation will significantly streamline the application process and prevent delays.
Methods of Application for 2026
The SSA provides several convenient ways to apply for benefits:
- Online: This is generally the easiest and fastest method for retirement benefits. You can apply from the comfort of your home.
- By Phone: You can call the SSA’s toll-free number to apply or schedule an appointment.
- In Person: Visit your local Social Security office. It’s often advisable to call ahead and schedule an appointment to minimize waiting times.
Each method has its advantages, but applying online is often recommended for its efficiency and ease of access. Remember to keep copies of all submitted documents and any correspondence with the SSA for your records.
Navigating Earnings Limits and Taxation in 2026
For many retirees, the decision to claim Social Security benefits doesn’t mean an end to working. Whether it’s part-time employment, consulting, or a new venture, earning income while receiving benefits introduces important considerations: earnings limits and taxation. Understanding how these factors interact with your 2026 Social Security Benefits is vital to avoid unexpected reductions or tax liabilities.
The Social Security Administration has specific rules regarding how much you can earn before your benefits are affected, particularly if you claim before your Full Retirement Age (FRA). Additionally, a portion of your Social Security benefits may be subject to federal income tax, depending on your combined income.
Social Security Earnings Limits for 2026
If you claim benefits before your FRA and continue to work, your benefits may be reduced if your earnings exceed a certain limit. These limits are adjusted annually. For 2026, the specific figures will be released closer to the year, but the general principles remain.
- Before FRA: If you are under your FRA for the entire year, the SSA will deduct $1 from your benefits for every $2 you earn above the annual limit.
- In the Year You Reach FRA: In the year you reach FRA, the SSA will deduct $1 from your benefits for every $3 you earn above a different, higher limit, but only for earnings before the month you reach FRA.
- At or After FRA: Once you reach your FRA, there are no earnings limits. You can earn as much as you want without your Social Security benefits being reduced.
It’s crucial to monitor these limits closely if you plan to work while receiving benefits, especially if you’re claiming early. Any benefits withheld due to earnings limits are not lost; they are added back to your future monthly payments once you reach your FRA.
Taxation of Social Security Benefits
A significant aspect of receiving Social Security benefits is understanding their potential taxability. Depending on your “combined income,” a portion of your benefits may be subject to federal income tax.
- Combined Income Calculation: This is your adjusted gross income (AGI) plus any tax-exempt interest (like municipal bond interest) plus one-half of your Social Security benefits.
- Taxation Tiers:
- If your combined income is between $25,000 and $34,000 for an individual ($32,000 and $44,000 for married filing jointly), up to 50% of your benefits may be taxable.
- If your combined income exceeds $34,000 for an individual ($44,000 for married filing jointly), up to 85% of your benefits may be taxable.
- State Taxes: Some states also tax Social Security benefits, so check your state’s specific tax laws.
Understanding these tax implications is essential for accurate financial planning and budgeting in retirement. Consulting a tax professional can help you navigate these rules and optimize your overall financial situation, ensuring you’re prepared for any tax liabilities associated with your benefits.
Advanced Strategies for Optimizing Your 2026 Social Security Benefits
Beyond the basic claiming decisions, there are several advanced strategies that can further optimize your 2026 Social Security Benefits, especially for couples and those with unique financial situations. These strategies often involve careful timing and coordination to maximize lifetime benefits for both individuals and their families. While complex, the potential gains can be substantial, making it worthwhile to explore these options.
These advanced approaches require a deeper understanding of Social Security rules and often benefit from personalized advice. They aim to leverage different benefit types and claiming ages to create a more robust retirement income stream, ensuring that you don’t leave any money on the table.
Coordinating Spousal Benefits
For married couples, coordinating when each spouse claims can yield higher combined lifetime benefits. This is particularly relevant if one spouse has a significantly higher earnings record.
- “Claim Now, Claim More Later”: While the “file and suspend” strategy is no longer available, a spouse with a lower PIA can still claim their own benefit early, allowing the higher-earning spouse to delay their claim until age 70. Once the higher earner claims, the lower-earning spouse can switch to a higher spousal benefit if it’s greater than their own.
- Strategic Delay for Higher Earner: Often, it makes sense for the higher-earning spouse to delay claiming until age 70 to maximize their benefit, which also maximizes the potential survivor benefit for their spouse. The lower-earning spouse might claim their own benefits earlier or spousal benefits if eligible.
These strategies require careful consideration of both spouses’ ages, health, and other retirement income sources. The goal is to create a plan that provides the highest possible income throughout both of their lives.
Considering Divorcee Benefits
Even after divorce, individuals may still be eligible for benefits based on their ex-spouse’s earnings record. This often comes as a surprise but can be a significant source of retirement income.
- Eligibility Criteria: You must have been married for at least 10 years, be currently unmarried, and be age 62 or older. Your ex-spouse must also be eligible for Social Security benefits (though they don’t necessarily have to be claiming them yet).
- No Impact on Ex-Spouse: Claiming benefits as a divorced spouse does not affect the benefits your ex-spouse or their current spouse receives.
This provision offers a valuable safety net for many, ensuring that a long-term marriage still provides some Social Security protection even after separation.
Impact of Working in Retirement
As discussed, working in retirement can affect your benefits if you claim before your FRA. However, it can also increase your future benefits. If your current earnings are higher than some of your past low-earning years, those new, higher earnings can replace older, lower-earning years in your 35-year calculation, potentially increasing your PIA.
These advanced strategies highlight the importance of personalized planning. Consulting with a financial advisor specializing in Social Security can help you identify and implement the best approach for your unique situation, ensuring you maximize every dollar of your Social Security entitlement.
| Key Point | Brief Description |
|---|---|
| Full Retirement Age (FRA) | Age to receive 100% of benefits; 67 for those born 1960 or later. |
| Early Claiming (Age 62) | Benefits are permanently reduced by up to 30% compared to FRA. |
| Delayed Claiming (Up to Age 70) | Benefits increase by 8% per year past FRA, up to age 70. |
| Spousal & Survivor Benefits | Provisions for eligible spouses and family members, with specific rules. |
Frequently Asked Questions About 2026 Social Security Benefits
You can claim Social Security benefits as early as age 62 in 2026. However, claiming at this age results in a permanent reduction of your monthly benefit compared to what you would receive at your Full Retirement Age (FRA).
Your FRA is crucial because it’s the age at which you receive 100% of your primary insurance amount. Claiming before your FRA reduces your benefits, while delaying past your FRA (up to age 70) increases them significantly due to delayed retirement credits.
Yes, you can work while receiving benefits. However, if you are under your FRA, your benefits may be temporarily reduced if your earnings exceed a certain limit. Once you reach your FRA, there are no earnings limits, and you can earn as much as you wish.
A portion of your Social Security benefits may be subject to federal income tax if your “combined income” exceeds certain thresholds. Some states also tax Social Security benefits, so it’s important to check your state’s tax laws.
Couples can maximize benefits through strategic coordination. This often involves the higher earner delaying their claim until age 70 to boost their own benefit and the potential survivor benefit, while the lower earner evaluates claiming their own or spousal benefits optimally.
Conclusion
Navigating your 2026 Social Security Benefits requires a proactive and informed approach. From understanding your Full Retirement Age to strategically choosing your claiming date, every decision impacts your long-term financial security. By leveraging the insights and practical solutions provided in this guide, you can confidently unlock your optimal Social Security benefits, ensuring a more stable and prosperous retirement. Remember, personalized planning is key, and seeking professional advice can further refine your strategy to meet your unique circumstances and goals.
