Maximizing 529 Plan Benefits 2026: Education Savings
Anúncios
Maximizing 529 plan benefits in 2026 involves understanding evolving tax laws, investment strategies, and qualified expenses to optimize education savings and minimize financial impact.
Anúncios
Navigating the landscape of education savings can be complex, but understanding how to maximize your 529 plan benefits in 2026 is crucial for securing your child’s academic future. This comprehensive guide will delve into the strategies and considerations essential for optimizing your educational investments.
Understanding the 529 Plan Landscape in 2026
The financial tools available for education savings are constantly evolving, and 2026 brings specific nuances to the 529 plan. These plans remain a cornerstone for many families aiming to cover higher education costs, offering significant tax advantages. However, staying informed about any legislative changes or new interpretations of existing rules is paramount to fully leveraging their potential.
A 529 plan is a tax-advantaged savings plan designed to encourage saving for future education costs. Sponsored by states, state agencies, or educational institutions, these plans come in two main forms: prepaid tuition plans and education savings plans. While prepaid plans allow you to lock in tuition rates at eligible in-state public colleges, education savings plans are more flexible, allowing funds to be used at almost any accredited post-secondary institution nationwide, and sometimes even abroad.
Key Features of 529 Plans
Understanding the core components of 529 plans is the first step toward effective maximization. These plans offer several attractive features that set them apart from other savings vehicles.
- Tax-Free Growth: Earnings in a 529 plan grow tax-free, meaning you won’t pay federal income tax on the investment gains as long as the withdrawals are used for qualified education expenses.
- Tax-Free Withdrawals: When funds are withdrawn to pay for qualified education expenses, they are also tax-free at the federal level. Many states also offer state income tax deductions or credits for contributions.
- Flexibility: The beneficiary of a 529 plan can be changed to another eligible family member without tax penalty, offering flexibility if initial plans change.
- Beneficiary Control: The account owner retains control over the funds, even after the beneficiary reaches adulthood, providing peace of mind.
In conclusion, the 529 plan environment in 2026 continues to offer robust opportunities for education savings. Familiarizing yourself with its fundamental structure and benefits is crucial for making informed decisions and setting a strong foundation for future financial planning.
Strategic Contributions: Optimizing Your Savings Schedule
Making smart contributions to your 529 plan is not just about how much you save, but also when and how often you contribute. A well-thought-out contribution strategy can significantly enhance the growth of your education fund, leveraging the power of compound interest and potential state tax benefits. This section explores various approaches to optimize your savings schedule for maximum impact.
Many families opt for regular, automatic contributions, which cultivate a disciplined savings habit and dollar-cost averaging. This strategy involves investing a fixed amount at regular intervals, regardless of market fluctuations. Over time, this can reduce the average cost per share and mitigate the risk of investing a large sum at an market peak.
Maximizing State Tax Benefits
One of the most compelling reasons to contribute consistently to a 529 plan is the potential for state income tax deductions or credits. While federal contributions are not deductible, many states offer incentives for residents. It’s essential to research your specific state’s 529 plan benefits, as rules and limits vary significantly.
- Annual Contribution Limits: Be aware of the annual gift tax exclusion, which allows individuals to contribute up to a certain amount (e.g., $18,000 in 2024, subject to inflation adjustments) per beneficiary without incurring gift tax.
- Front-Loading Contributions: For those with significant lump sums, the five-year gift tax election allows you to contribute up to five years’ worth of gift tax exclusions at once (e.g., $90,000 in 2024) without incurring gift tax, accelerating tax-free growth.
- Employer Contributions: Some employers offer matching contributions or payroll deductions for 529 plans. If available, this is an excellent way to boost your savings with minimal effort.
By strategically planning your contributions, you can not only build a substantial education fund but also take advantage of valuable tax incentives. Regular reviews of your financial situation and state tax laws will ensure your contribution strategy remains optimized.
Investment Strategies Within Your 529 Plan for 2026
The investment choices within your 529 plan play a critical role in its growth trajectory. In 2026, understanding the available investment options and aligning them with your risk tolerance and timeline is crucial for maximizing returns. 529 plans typically offer a range of portfolios, from aggressive to conservative, often with age-based options.
Age-based portfolios are a popular choice for many families. These portfolios automatically adjust their asset allocation as the beneficiary gets closer to college age, gradually shifting from more aggressive investments (like stocks) to more conservative ones (like bonds and cash equivalents). This approach helps to mitigate risk as the need for funds approaches.
Anúncios
Diversifying Your 529 Investments
Even within the confines of a 529 plan, diversification remains a key principle of sound investing. Spreading your investments across different asset classes can help reduce risk and potentially enhance returns over the long term. Consider the following when making your investment selections:
- Equity Funds: These funds invest primarily in stocks and offer the potential for higher returns, but also come with greater volatility. They are generally suitable for younger beneficiaries with a longer time horizon.
- Fixed-Income Funds: Investing in bonds and other debt instruments, these funds offer lower risk and more stable returns, making them suitable as the beneficiary approaches college age.
- Money Market Funds: These are the most conservative option, offering minimal risk and liquidity, ideal for funds needed in the very short term.
- Target-Date Funds: Similar to age-based portfolios, these funds automatically rebalance their asset allocation based on a specific target date, such as the year the beneficiary is expected to start college.
Regularly reviewing your investment choices and making adjustments as circumstances change or market conditions shift is essential. While you are typically limited to two investment changes per calendar year, this flexibility allows for strategic adjustments to keep your plan on track.
Qualified Education Expenses: What’s Covered in 2026?
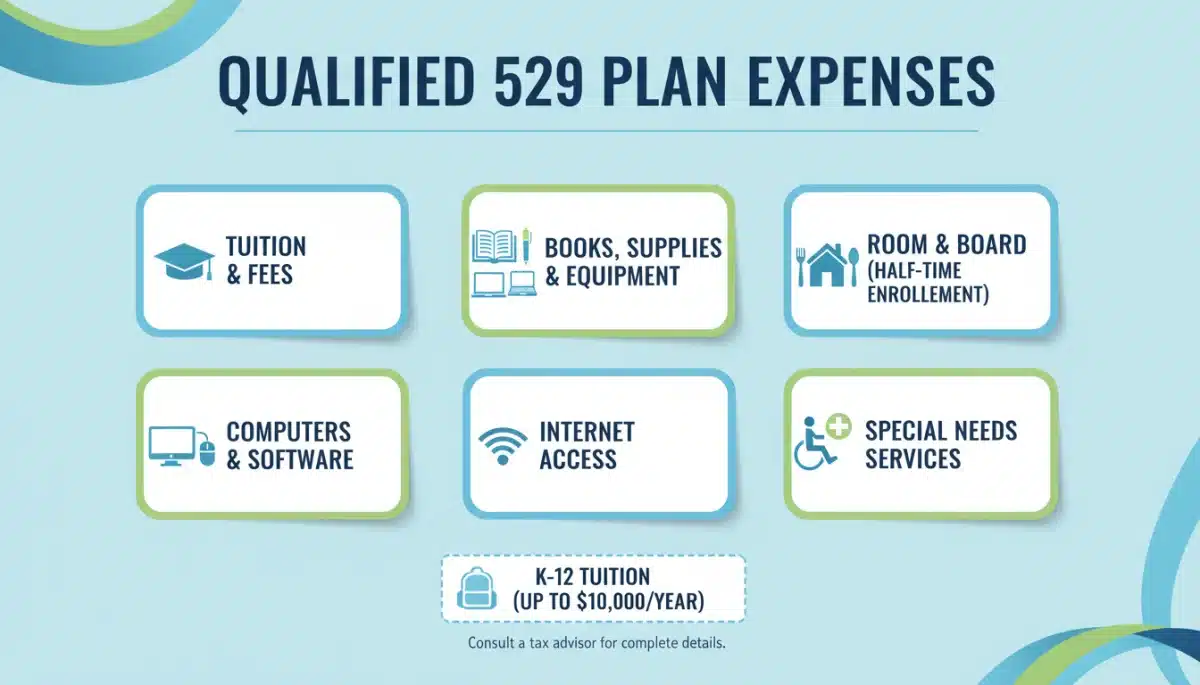
One of the most critical aspects of maximizing your 529 plan benefits is understanding what constitutes a qualified education expense. Using funds for non-qualified expenses can result in taxes on earnings and a 10% penalty. In 2026, the definition of qualified expenses remains broad, encompassing a variety of costs associated with higher education and even some K-12 expenses.
Generally, qualified education expenses include tuition, fees, books, supplies, and equipment required for enrollment or attendance at an eligible educational institution. This also extends to expenses for special needs services incurred in connection with enrollment or attendance. The institution must be eligible to participate in federal student aid programs, which includes most accredited public and private colleges, universities, and vocational schools.
Beyond Tuition and Books
The scope of qualified expenses often extends beyond the most obvious categories. Being aware of these broader allowances can help families utilize their 529 funds more effectively.
- Room and Board: If the student is enrolled at least half-time, costs for room and board are considered qualified expenses, up to the allowance determined by the institution for federal financial aid purposes. This includes both on-campus housing and off-campus rent and utilities.
- Computers and Related Equipment: The cost of a computer, peripheral equipment, software, or internet access is a qualified expense if it is used primarily by the beneficiary during any of the years the beneficiary is enrolled at an eligible educational institution.
- K-12 Tuition: Up to $10,000 per year per student can be withdrawn tax-free from a 529 plan to cover tuition expenses for K-12 public, private, or religious schools.
- Apprenticeship Programs: In recent years, qualified apprenticeship program expenses have also been added to the list of eligible uses for 529 funds, providing more flexibility for career-focused education.
It’s always advisable to keep thorough records of all education-related expenses and withdrawals. Consulting with a tax professional can also provide clarity on specific situations and ensure compliance with IRS regulations, preventing unexpected tax liabilities.
Navigating Financial Aid and 529 Plans in 2026
A common concern for families saving with a 529 plan is its impact on financial aid eligibility. While 529 plans are considered an asset, their treatment in financial aid calculations is generally favorable compared to other types of savings. Understanding these nuances in 2026 is crucial for balancing savings with potential aid opportunities.
For federal financial aid purposes, 529 plans owned by a dependent student or one of their parents are generally reported as a parent asset. Parent assets are assessed at a maximum of 5.64% in the Expected Family Contribution (EFC) calculation, which is significantly lower than student assets, which are assessed at 20%. This means a 529 plan has a relatively minor impact on aid eligibility compared to funds held directly in the student’s name.
Strategies to Minimize Financial Aid Impact
While 529 plans do have some impact, there are strategies families can employ to further minimize their effect on financial aid eligibility.
- Grandparent-Owned 529 Plans: A 529 plan owned by a grandparent or other non-parent relative is not reported as an asset on the FAFSA. However, withdrawals from such plans are considered untaxed income to the student in the year they are received, which can significantly reduce aid eligibility in subsequent years. A common strategy is to delay these withdrawals until the student’s final year of college.
- Timing of Withdrawals: If you anticipate needing financial aid, it might be strategic to use 529 funds for earlier college years and save other assets, if available, for later years.
- Understanding FAFSA Simplification: Be aware of any ongoing changes to the FAFSA (Free Application for Federal Student Aid) and its methodologies, as these can influence how 529 plans are assessed. The FAFSA Simplification Act, for example, has introduced changes to how certain assets and income are treated.
Ultimately, the benefits of tax-advantaged growth and tax-free withdrawals from a 529 plan often outweigh the modest impact on financial aid eligibility. It’s a powerful tool that, when managed strategically, can significantly reduce the overall cost of education.
Advanced 529 Plan Strategies and Considerations for 2026
Beyond the fundamental aspects of 529 plans, there are several advanced strategies and considerations that can further enhance their utility and financial impact in 2026. These approaches often cater to specific financial situations or long-term planning goals, offering greater flexibility and optimization.
One such advanced strategy involves using a 529 plan for yourself. Many adults pursue continuing education, graduate degrees, or career changes that require new skills. A 529 plan can be a valuable tool for funding these personal educational pursuits, offering the same tax advantages as saving for a child’s education.
Exploring Unique 529 Plan Uses
- 529-to-Roth IRA Rollovers: Beginning in 2024, a new provision allows for tax-free rollovers from a 529 plan to a Roth IRA for the beneficiary, subject to certain conditions. This offers an alternative if the beneficiary decides not to pursue higher education or has leftover funds. There are limits on the amount that can be rolled over annually and a lifetime cap, and the 529 account must have been open for at least 15 years.
- Student Loan Repayment: Up to $10,000 in student loan repayments (per beneficiary, lifetime limit) can be made from a 529 plan without federal income tax or penalty. This provides a valuable option for managing student debt.
- Gift Tax Planning: For high-net-worth individuals, 529 plans can be an effective estate planning tool. Contributions are considered completed gifts, removing assets from the donor’s taxable estate, while the donor retains control over the assets.
These advanced strategies highlight the evolving nature and increasing flexibility of 529 plans. Staying informed about legislative updates and consulting with a financial advisor can help you integrate these tools into a comprehensive financial plan, ensuring you maximize every available benefit for education savings and beyond.
| Key Aspect | Description |
|---|---|
| Tax Advantages | Tax-free growth and withdrawals for qualified education expenses; potential state tax benefits. |
| Qualified Expenses | Tuition, fees, books, room/board, computers, K-12 tuition up to $10k, apprenticeships. |
| Financial Aid Impact | Treated as parent asset, assessed at lower rate (max 5.64%); less impact than student assets. |
| Advanced Uses | 529-to-Roth IRA rollovers, student loan repayment, estate planning benefits. |
Frequently Asked Questions About 529 Plans in 2026
In 2026, 529 plans continue to offer tax-free growth on investments and tax-free withdrawals for qualified education expenses at the federal level. Many states also provide additional tax incentives, such as deductions or credits for contributions, further enhancing their financial appeal for education savings.
Yes, as of 2026, you can withdraw up to $10,000 per year, per beneficiary, from a 529 plan to cover tuition expenses for K-12 public, private, or religious schools. These withdrawals are tax-free at the federal level, offering significant flexibility for families with younger students.
529 plans owned by a parent or dependent student are generally considered parent assets on the FAFSA. They are assessed at a maximum of 5.64% in the Expected Family Contribution calculation, which is a relatively small impact compared to student-owned assets, making them a favorable savings vehicle.
If there are leftover 529 funds, you have several options. You can change the beneficiary to another eligible family member, save the funds for future educational pursuits, or use up to $10,000 lifetime for student loan repayment. Additionally, 529-to-Roth IRA rollovers are now possible, subject to specific rules.
Beyond traditional college expenses and K-12 tuition, 529 plans can be used for qualified apprenticeship program expenses. A significant new development is the ability to roll over unused 529 funds into a Roth IRA for the beneficiary, offering an alternative savings path if education plans change, under specific conditions.
Conclusion
Maximizing 529 plan benefits in 2026 requires a proactive and informed approach. By understanding the tax advantages, strategically planning contributions, making wise investment choices, and staying abreast of qualified expenses and legislative updates, families can build a robust education fund. These plans remain an indispensable tool for navigating the rising costs of education, offering flexibility and significant financial advantages that, when fully leveraged, can secure a brighter academic future for beneficiaries.
